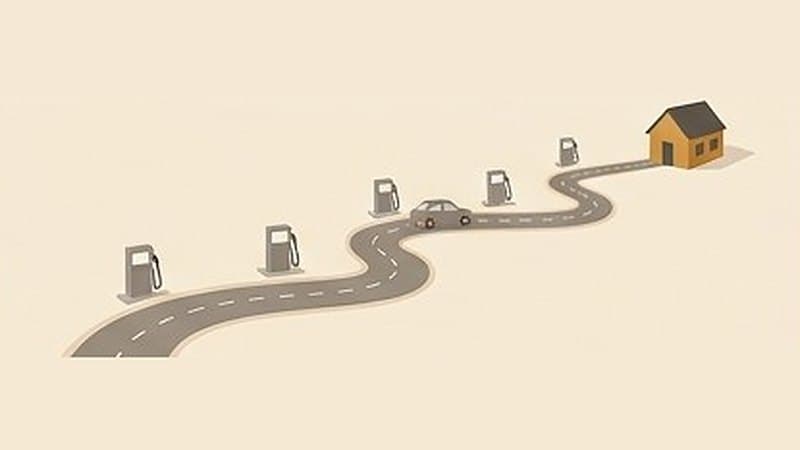
The last lesson used a 25-year example, but almost nobody signs a 25-year contract. Canadian mortgages are borrowed in shorter chunks called terms, and the choices you make for each term shape what you pay and how flexible you can be.
Term versus amortization
The amortization is the full payoff timeline. The term is your current contract with the lender: the rate, the rules and the penalties you've agreed to for a set period. Five years is the most common term in Canada, but one to ten years are all available.
A useful way to picture it: the amortization is the whole road trip, and each term is one tank of gas. When the tank runs out, you stop, look at the prices, and fill up again, possibly at a different station.
In the last lesson's example, $400,000 over 25 years leaves about $349,700 owing after a 5-year term. That balance doesn't disappear. It's renewed for a new term at whatever rates are available that day.
Fixed rates
A fixed rate stays the same for the whole term, and so does the payment. That certainty is the main appeal.
Fixed rates are priced off Government of Canada bond yields, so they can move even when the Bank of Canada does nothing. The trade-off for the certainty is a potentially larger penalty if you break the term early, which the lesson on refinancing and breaking a mortgage covers.
Variable rates
A variable rate is usually set as the lender's prime rate plus or minus a discount, for example prime minus 0.95%. Prime follows the Bank of Canada's policy rate, so when the Bank moves, your rate moves within days.
Variable mortgages come in two styles. With an adjustable payment, the payment changes whenever prime changes. With a fixed payment, the payment stays put and the split between interest and principal shifts instead. If rates rise far enough, the whole payment can end up going to interest. That point is called the trigger rate.
Open versus closed, and prepayments
Most mortgages are closed: you agree not to pay off more than a set amount early without a penalty. Open mortgages let you pay any amount at any time, but the rate is noticeably higher.
Closed mortgages usually still include prepayment privileges, such as paying an extra 10% to 20% of the original balance each year or raising the payment. Every lender's rules differ, so the mortgage documents are the place to confirm yours. Even modest prepayments can take years off the amortization. There's more in our post on prepayment privileges.
What happens at renewal
As the term ends, federally regulated lenders must send a renewal statement at least 21 days beforehand, setting out the new rate and terms they're offering. You can accept it, negotiate, or move the mortgage to another lender. Switching at renewal doesn't trigger a prepayment penalty, though there can be modest legal or appraisal costs, which the new lender sometimes covers.
The first renewal offer isn't always the lender's best one. Comparing a few offers is a normal part of the process, not a confrontation.
A rough rule of thumb for planning: on a 20-year remaining amortization, each percentage point of rate change moves the payment by about $50 a month per $100,000 owed. That's an estimate, but it's useful for a first sense of what a renewal might do to a budget. Our post on renewal payments works through four situations in detail.
Try it
One amortization, five terms
The same $400,000 over 25 years, borrowed in five 5-year terms at 4.25%. Each dot is a renewal, where the remaining balance gets a new rate.
Payment in term 1
$2,159
at 4.25%
Payment in term 2
$2,346
at 5.25%
Change each month
+$187
more than before
Where to go next
That's the mortgage itself. The next module turns to buying a home: saving the down payment, what it costs to close, and how lenders decide how much you can borrow.
Worked figures are estimates based on the example inputs shown, checked October 11, 2026. Rates, rules and lender policies change, and your own numbers will differ. This is educational information, not financial advice.